
Guides · Buying
How much down payment do you actually need in Seattle?
Almost certainly less than you have been told. And the number you have been quoted is probably the loan minimum, which is not the same as what you bring to closing. Seattle-area buyers may qualify for down payment help on top of a low-down-payment loan, and that help can change what you bring to closing.
What a down payment actually is#
The 20% number is not a rule#
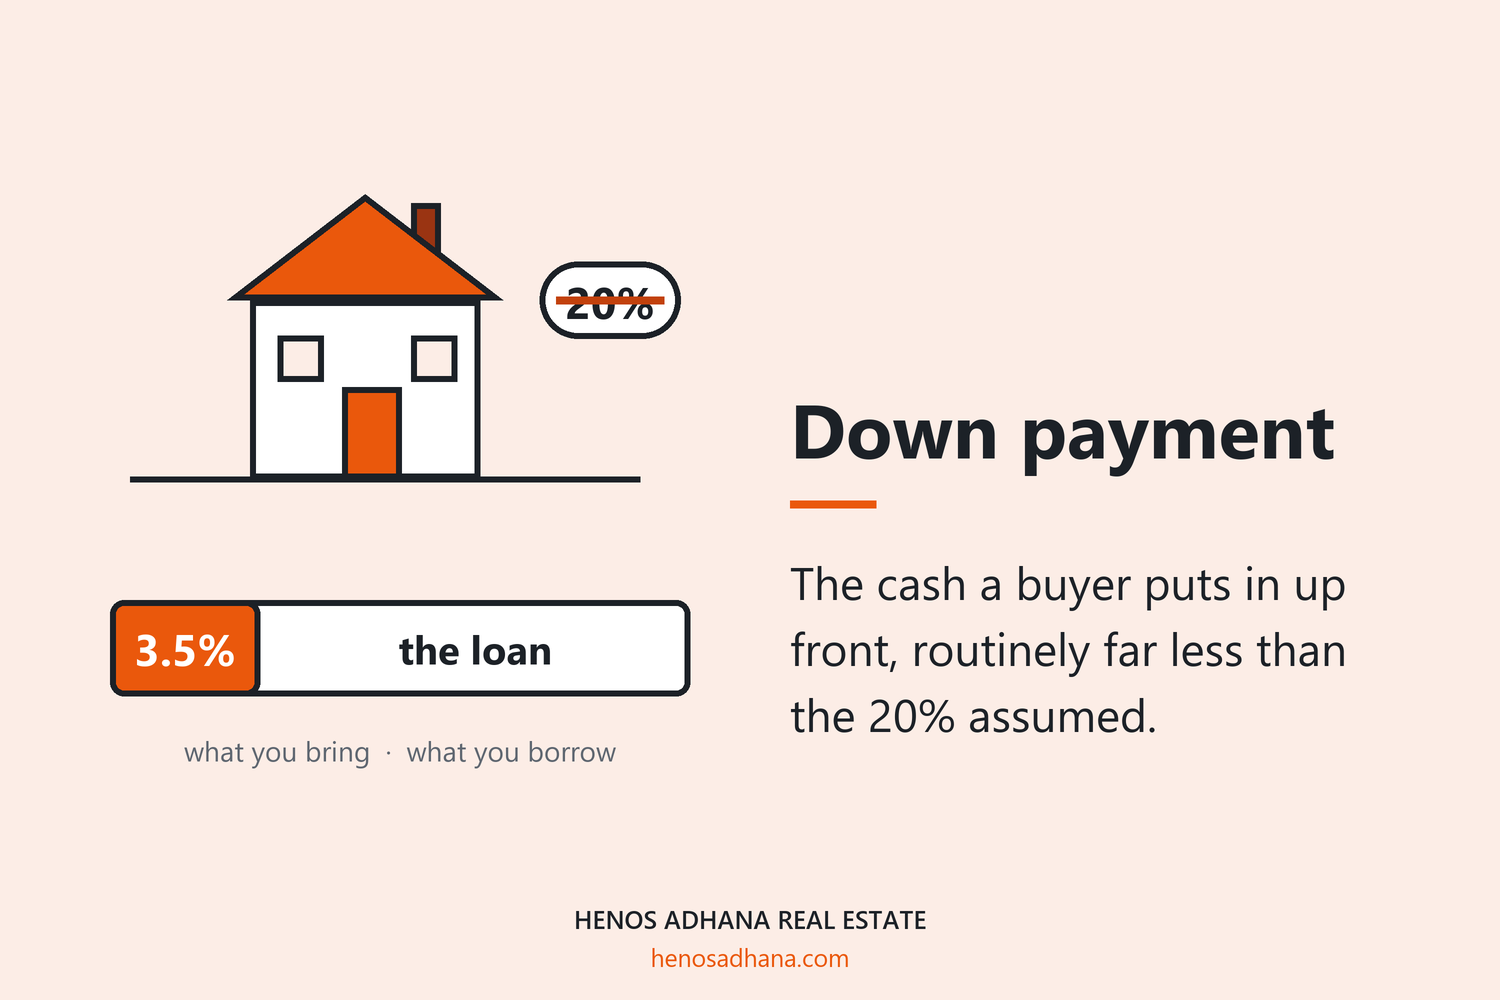
Twenty percent is not a requirement. It is the threshold above which you stop paying mortgage insurance, which is a different thing entirely. Treating it as the price of entry is the single most common reason people who could buy here decide they cannot.
The loan programs set their own minimums, and they are far lower. What matters is that a loan minimum tells you what the lender requires. Not what comes out of your account.
Wondering what this means for your budget?
Book a 30-minute buying callDown payment help in Seattle#
Down payment help is not a fringe program. The City of Seattle Office of Housing offers it to buyers who earn less than 80% of area median income, through local nonprofit partners. The City page says the City can give up to $76,000 per household. Two partners on that page list their own amounts. HomeSight says buyers may get up to $70,000. Parkview Services says eligible buyers may get as much as $110,000 by layering more than one down payment source. The City page does not say which programs you can combine, so ask the partner and your lender before you count on more than one.
Most buyers only hear about the loan minimum. Local help can change what you bring to closing, so check it early.
The City program has clear rules. Your household must earn less than 80% of area median income for its size. You must not have owned a home in the last 3 years. The home must be inside Seattle city limits and must be your main home. You must take a homebuyer class and meet one-on-one with a housing counselor. The state's Home Advantage programs have their own rules. Their down payment loans are repaid when you sell, refinance, move out or pay off your mortgage.
Sources
- Buy a home, down payment assistance, City of Seattle Office of Housing
- Home Advantage and downpayment assistance programs, Washington State Housing Finance Commission
A common low-down-payment pairing#
One common way to buy with little down is 3.5% down on an FHA loan, paired with WSHFC Home Advantage. FHA sets a low bar to qualify, and the state program can help with what you owe at closing.
VA is the other one worth knowing about. For eligible service members and veterans, the down payment can be zero. Because it only applies to them, general advice often leaves it out.
Program terms, income limits and rates change. Treat the structure here as the map and confirm the current numbers before you plan around them.
One thing worth saying plainly: City of Seattle help is a separate program from the state's, with its own rules. Whether you qualify for it is a real question with a real answer, and it is one of the first things worth checking together.
What else you need at closing#
The down payment is not the whole number, and pretending otherwise sets people up to be blindsided. Budget separately for closing costs, prepaid taxes and insurance, the inspection, the appraisal, and some reserve after you close.
Some of these are negotiable. Seller-paid closing costs are a normal thing to ask for, and in the right market conditions they are achievable. Which effectively lowers what you bring even when the down payment itself does not move.
The less common paths#
Two others come up, and both deserve a straight answer rather than enthusiasm.
Seller financing, where the seller carries the note instead of a bank, is real, and it does happen, most often with investment property, land, or between parties who already know each other. It is uncommon in ordinary residential sales, and there are federal limits on how often an individual can do it before they are treated as a lender. If it comes up, it is an attorney conversation before it is a strategy.
Rent-to-own, or a lease with an option to buy, is the one to be most careful with. The structure is simple enough: you rent, usually above market, with part of each payment credited toward a future purchase. The risk is that the credit is conditional. Miss payments, or fail to qualify for a mortgage when the option comes due, and you can lose both the accumulated credit and the up-front option fee. There is a long history of these arrangements being used against buyers who cannot get conventional financing.
None of that makes it automatically bad. It makes it something to have reviewed, with a title check done before you sign rather than at the end, and terms you have had a lawyer read. If someone is pushing you toward it and discouraging review, that is your answer.
Common questions#
Do I need 20% down to buy in Seattle?
No. Twenty percent is the point at which mortgage insurance drops off, not a requirement to buy. Loan minimums are far lower, and assistance programs can reduce what you bring further.
Does down payment assistance have to be repaid?
Usually, yes. The City partners describe low-interest loans and deferred second mortgages. The state's down payment loans are repaid when you sell, refinance, move out or pay off your first mortgage. Terms differ by program, so check the specific one rather than assuming.
Am I still a first-time buyer if I owned a home years ago?
Often yes. Most programs define it as not having owned a primary residence in the last three years, so people who owned before that frequently still qualify. It is worth checking rather than ruling yourself out.
Is a lower down payment worth the higher monthly payment?
Sometimes. Putting less down means a larger loan and usually mortgage insurance, but it also means buying sooner and keeping reserves. Which one wins depends on your numbers, not on a general rule. That is a conversation worth having before you shop.
Related guides
- What buying in Seattle actually costs: the Seattle buyer's guide
- Seattle mortgage payment calculator, with taxes and insurance
- Pre-qualified, pre-approved or fully underwritten: which one a Seattle offer needs